
Growth is exciting. More ads, more hires, more inventory, more markets, more automation: these moves can make a young business look serious very quickly. But scale does not repair a weak business model. It usually makes the weakness larger, faster, and more expensive.
Unit economics is the practical discipline of asking whether one additional customer, order, subscription, or job creates enough value after its direct costs. It suits founders building software, ecommerce brands, marketplaces, agencies, service businesses, and side hustles alike. The “unit” changes; the logic does not.
This matters now because customer acquisition is rarely free, suppliers can change prices, and cash constraints make vague optimism costly. You do not need a finance degree or a perfect spreadsheet. You need an honest view of what happens every time you make another sale.
Think of unit economics as the dashboard before the accelerator. Once you know which customers are profitable, why they buy, and how long cash takes to return, growth becomes a decision you can make with more confidence rather than a gamble dressed up as ambition.
🧭 1. Start With the Question That Actually Matters
The core question is simple: does each additional unit of business generate enough gross profit to cover the cost of winning, serving, and retaining that customer?
A profitable order is not automatically a profitable company. Your contribution from each order must eventually pay for overhead such as salaries, software, rent, insurance, accounting, and your own time.
Use a clear definition of “unit”
- A SaaS company may use one paying account or one subscriber-month.
- An online store may use one completed order.
- A consultant may use one client project or one billable day.
- A marketplace may use one completed transaction.
- A local service may use one appointment or one recurring customer-month.
Choose one primary unit and keep it consistent. Changing the definition whenever results look inconvenient is a fast route to misleading conclusions.
🔎 2. Separate Revenue From Cash
Revenue records what you earned under your accounting approach. Cash records what entered and left your bank account. Both matter, especially when you are paying suppliers before customers pay you.
A business can show attractive revenue and still struggle to make payroll. This is common with wholesale, project work, subscriptions with annual costs, and physical products that require inventory upfront.
Ask these cash questions
- When do customers pay: upfront, on delivery, or 30 to 90 days later?
- When must you pay suppliers, contractors, platforms, and ad bills?
- Do refunds, chargebacks, returns, or unpaid invoices create delays?
- How much working capital is required for the next month of growth?
Track your bank balance alongside profit metrics. A healthy margin is valuable, but a business still needs enough cash to survive the journey to that margin.
🧮 3. Learn the Four Numbers Behind Most Decisions
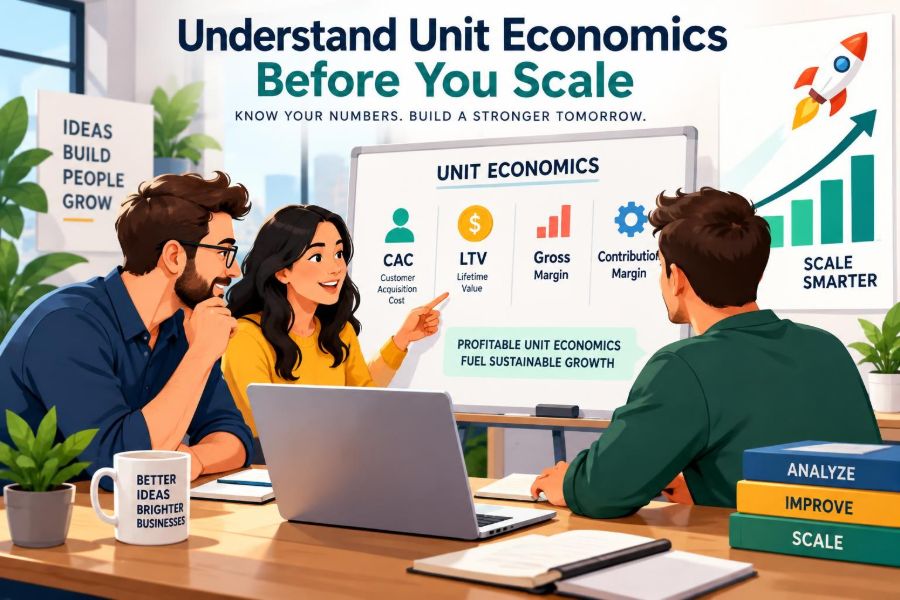
You can understand an enormous amount of a startup’s health with four measures: average revenue per unit, variable cost per unit, contribution margin, and customer acquisition cost.
| Metric | Simple calculation | What it tells you |
|---|---|---|
| Average revenue per unit | Total revenue ÷ units sold | What a typical sale or customer produces |
| Variable cost per unit | Total direct variable costs ÷ units sold | What rises as each additional unit is sold |
| Contribution margin | Revenue per unit − variable cost per unit | What remains to acquire customers and fund overhead |
| Customer acquisition cost | Sales and marketing spend ÷ new customers | What it costs to win each new customer |
Do not obsess over decimal-level precision in week one. Build a usable first version, document assumptions, and improve it as actual data arrives.
💵 4. Calculate Contribution Margin Before Overhead
Contribution margin is the money left from a sale after the direct costs required to make and deliver it. It is not net profit. It is the amount available to contribute toward fixed costs and profit.
For a product business, direct costs can include product cost, packaging, payment processing, delivery subsidies, fulfillment, returns, and marketplace fees. For a service, they may include contractor labor, travel, booking fees, and materials.
A simple example
Imagine a business sells a digital workshop for $120. Payment processing costs $4, a facilitator costs $30 per attendee, and customer support costs an estimated $6 per attendee. Contribution margin is $80, or about 67% before marketing and overhead.
If it costs $95 in advertising and sales effort to acquire that attendee, the first purchase loses $15 before overhead. That could still work if the customer reliably buys a profitable follow-up offer, but it is not a healthy one-off sale.
🏷️ 5. Treat Pricing as a Unit-Economics Lever
Many early founders price by copying competitors or charging what feels polite. Customers care about value, alternatives, trust, and outcomes; they do not see your discomfort. Price must support the business required to deliver the promise.
Raising price is not always the answer. But if your margins are thin, your offer is poorly packaged, or your buyer is a poor fit, adding more volume can create more work without enough reward.
Test pricing thoughtfully
- State the specific problem and outcome your offer addresses.
- Create packages based on meaningful differences, not arbitrary feature clutter.
- Check whether discounts attract profitable repeat buyers or price-sensitive churn.
- Include taxes, payment fees, refunds, and delivery costs in your calculation.
- Speak to prospects before assuming a lower price is the barrier.
Tax treatment and pricing rules vary by country and product type. Get local professional advice when you are collecting sales taxes, VAT, GST, or operating in regulated categories.
📦 6. Count Every Truly Variable Cost
The most common spreadsheet error is leaving out inconvenient costs. If a cost rises materially when sales rise, it belongs in your unit model, even if the bill arrives later or comes from a different team.
Commonly missed costs
- Refunds, returns, replacements, and chargebacks
- Free shipping and failed delivery attempts
- Payment processing and currency conversion fees
- Affiliate commissions and sales commissions
- Onboarding, implementation, and support labor
- Cloud usage, third-party API usage, and transaction fees
- Packaging, samples, spoilage, and inventory write-downs
Estimate uncertain items conservatively. It is better to be pleasantly surprised than to scale based on a margin that only exists because key costs were ignored.
🎯 7. Measure Customer Acquisition Cost by Channel
Blended customer acquisition cost, or CAC, is useful as a broad headline. It can also hide a major problem: one channel may produce excellent customers while another burns money.
Calculate channel CAC whenever possible. Include ad spend and the directly attributable people, tools, commissions, creative, and agency costs needed to obtain customers from that channel.
Channel CAC example
| Channel | Estimated acquisition cost | Likely strength | Watch-out |
|---|---|---|---|
| Founder outreach | Low cash, high time | Fast learning and strong feedback | Hard to scale without a process |
| Paid advertising | Variable | Fast testing and controllable volume | Costs can rise quickly |
| Content and search | Upfront effort | Compounds over time | Slow and uncertain early results |
| Partnerships | Often moderate | Borrowed trust and targeted reach | Longer sales cycles |
Do not label a channel “cheap” because cash spend is low if it consumes a large share of your week. Founder time is limited, and eventually it has a real replacement cost.
🔁 8. Understand Lifetime Value Without Fantasy
Lifetime value, often called LTV, estimates gross profit from a customer over the relationship. It is especially useful for repeat-purchase and subscription businesses, but it becomes dangerous when built on unproven retention assumptions.
Start with realized behavior. If you have only two months of data, say so. Use a cautious range rather than claiming customers will stay for years because you hope they will.
A grounded LTV approach
- Calculate average gross profit per customer per month or per order.
- Measure repeat purchase or retention by customer cohort.
- Subtract costs associated with serving, retaining, and supporting customers.
- Build a low, base, and high scenario.
- Make decisions from the low or base case, not the optimistic case.
LTV is not a permission slip to lose money indefinitely. It is a hypothesis that needs evidence from retention, repayments, repeat orders, and actual gross margin.
⏱️ 9. Track CAC Payback, Not Just LTV to CAC
A favorable LTV-to-CAC ratio can still conceal a cash problem. If you pay $300 to acquire a customer but recover that amount only after 18 months, you need enough capital and retention confidence to carry the delay.
CAC payback period is the time required for contribution margin from a customer to repay the cost of acquiring them. Shorter payback generally gives a young business more flexibility.
For example, a customer acquired for $150 who contributes $50 monthly pays back in roughly three months before considering broader overhead. If that same customer contributes $10 monthly, payback is about 15 months. The customer may be valuable long term, but the funding needs are entirely different.
📈 10. Watch Retention and Churn Like a Founder
Acquisition gets attention because it feels like growth. Retention determines whether you are filling a bucket or building an asset. If customers leave quickly, spending more to acquire them usually accelerates the leak.
For subscriptions, measure customer and revenue churn. For commerce, measure reorder rate and time to second purchase. For services, measure renewal rate, referrals, and expansion into additional work.
Practical retention questions
- Which customer segment stays longest and why?
- What happens in the first day, week, or month after purchase?
- What is the most common reason for cancellation or return?
- Are customers achieving the outcome you sold?
- Does your onboarding create momentum or confusion?
Talk to people who leave. Their feedback will not always be pleasant, but it is often more useful than another month of guessing inside your spreadsheet.
🧪 11. Build a Simple Unit-Economics Spreadsheet
You do not need complex financial software to begin. A spreadsheet with a few tabs can turn vague opinions into explicit assumptions worth testing.
Set up these tabs
- Inputs: price, fees, direct labor, product costs, return rate, and acquisition assumptions.
- Unit model: revenue, variable costs, contribution margin, CAC, payback, and scenario outputs.
- Actuals: weekly or monthly results imported from sales, ads, payment, and support records.
- Cohorts: customers grouped by purchase month or source to monitor retention and repeat behavior.
- Decisions: a short log of what you changed, why, and what happened.
Use formulas that you can explain in plain language. A beautiful model no one trusts or understands is less useful than a plain one your team updates every Friday.
🧱 12. Separate Fixed Costs From Variable Costs
Fixed costs do not change much in the short term as sales change. Examples include baseline salaries, rent, annual software subscriptions, insurance, and accounting. Variable costs rise as you sell more.
The distinction is not perfect. A support salary may be fixed today but require another hire at a certain customer threshold. That is why capacity planning matters alongside a basic margin calculation.
Use contribution to calculate break-even
If monthly fixed costs are $8,000 and contribution margin per order is $40, you need about 200 orders per month to cover those costs. This is a planning estimate, not a prediction, but it makes your operating reality visible.
Now test what happens if returns rise, shipping costs increase, or discounting reduces contribution to $28. The break-even volume rises sharply. Small margin changes have big consequences when multiplied across a business.
⚖️ 13. Know When Low Margins Can Still Work
Low-margin businesses are not automatically bad businesses. Grocery, distribution, marketplaces, and high-volume services can work with lower margins if they have fast inventory turns, efficient operations, repeat demand, favorable payment terms, and disciplined overhead.
But low margins leave less room for errors. A modest refund spike, supplier price increase, or paid-advertising decline can remove profit quickly.
Lower margins require stronger operations
- Reliable demand and repeatable fulfillment
- Accurate inventory and purchasing discipline
- Clear controls on waste, refunds, and fraud
- Healthy cash conversion cycles
- Enough volume to cover operating complexity
If you are early, a higher-margin niche can be easier to test because you need fewer sales to learn whether the model has promise.
🚩 14. Spot the Red Flags Before You Scale
Scaling should amplify a repeatable advantage. Pause when the numbers suggest you are buying revenue rather than building an economic engine.
Warning signs worth taking seriously
- CAC is rising while conversion rates and retention are falling.
- Customers buy once but do not return or refer others.
- Discounts are needed to close nearly every sale.
- Contribution margin disappears after returns, support, and fulfillment.
- Revenue grows but bank balance consistently worsens.
- Each new customer requires disproportionate founder involvement.
- Your model relies on untested long-term LTV assumptions.
A red flag is not proof that the business must end. It is a signal to investigate, narrow the target market, adjust the offer, cut a channel, or redesign the operating model before committing more capital.
🛠️ 15. Improve the Model One Lever at a Time
When unit economics are weak, founders often react by changing everything: price, audience, product, ads, brand, team, and platform. Then they cannot tell what actually helped.
Pick the largest constraint and run a defined experiment. For instance, if paid CAC is too high, improve the landing page for one audience segment, change one offer element, and compare results over a meaningful period.
The main levers
- Increase price or improve package mix.
- Reduce direct delivery, payment, or fulfillment costs.
- Improve conversion from qualified leads.
- Lower CAC by improving targeting, referrals, or partnerships.
- Increase retention, repeat purchase, and expansion revenue.
- Reduce refunds by setting clearer expectations and improving quality.
Improve the underlying customer value first. Tricks may change a dashboard temporarily; a better outcome for the right customer tends to improve several metrics at once.
👥 16. Segment Customers Instead of Trusting Averages
An average customer can be imaginary. One segment may have excellent retention and low support needs while another buys only during discounts, returns frequently, and absorbs your team’s attention.
Segment the data by acquisition channel, product, location, company size, use case, purchase month, or customer profile. Start with a few meaningful categories rather than creating an analysis project nobody maintains.
What to look for
- Which segment has the highest contribution margin?
- Which segment reaches payback fastest?
- Which source brings repeat buyers?
- Which customers require expensive onboarding or support?
- Which group is most likely to recommend you?
Your best growth move may be serving fewer types of customers more deeply. Focus is not a lack of ambition; it is often the path to a clearer, more scalable model.
🤝 17. Include Human Capacity in Service Businesses
Services can look profitable until you calculate delivery time honestly. If you charge $1,000 for a project but spend 35 hours delivering it, handling revisions, selling it, and managing the client, the effective economics may be far weaker than the invoice suggests.
Track hours by activity for a few weeks. Include sales calls, proposals, administration, communication, rework, travel, and post-project support.
Ways to improve service economics
- Standardize a repeatable offer with clearer scope.
- Use deposits, milestone billing, or retainers to improve cash flow.
- Build templates, checklists, and onboarding systems.
- Raise prices only alongside a credible value proposition and positioning.
- Delegate defined, documented tasks when margin supports it.
Do not hire simply because you are busy. Hire when demand is sufficiently reliable and the delegated work has a documented process that protects quality and margin.
📊 18. Create a Weekly Founder Scorecard
Metrics only help when they influence behavior. A short weekly scorecard creates a rhythm for noticing changes before they become expensive surprises.
Track a practical minimum set
- New customers, orders, or activated accounts
- Revenue and cash collected
- Average selling price
- Contribution margin in dollars and percentage
- CAC by major channel
- Repeat purchase, retention, or churn
- Refunds, returns, support volume, and delivery time
- Cash runway and upcoming major payments
Review trends, not just a single noisy week. Then write one decision: continue, stop, fix, or test. The scorecard is not for impressing investors or yourself; it is for running the business better.
🚀 19. Define What “Ready to Scale” Means
Scale is not a feeling and it is not simply a growing social following. You are closer to ready when a specific customer segment buys a clearly valuable offer through a repeatable channel at economics that can support additional volume.
That does not mean everything must be perfect. It means you understand the major unknowns, have enough cash or financing for the payback period, and have processes that will not collapse when demand doubles.
A practical readiness checklist
- Your contribution margin remains positive after realistic direct costs.
- You can explain CAC and where it comes from.
- Retention or repeat behavior supports your LTV assumption.
- You know your capacity constraints and next hiring or inventory trigger.
- You have tested the economics across more than one time period.
- You can fund growth without creating a hidden cash emergency.
Funding, credit, and tax obligations carry real risks. Consider qualified financial and legal advice before signing major commitments, especially where regulations, lending terms, employment rules, or consumer protections apply.
✅ 20. Your Action Plan for This Week
Do not wait for perfect data. Give yourself one focused week to make the economics visible.
- Choose your unit: one order, customer, subscriber-month, appointment, or project.
- List every direct cost associated with that unit, including refunds and support.
- Calculate contribution margin using your last month of actual sales.
- Calculate CAC for your one or two biggest acquisition channels.
- Review repeat purchases, retention, or churn for your last few customer cohorts.
- Identify the single weakest assumption and schedule one experiment to test it.
- Set a 30-minute weekly scorecard review on your calendar.
Before you try to scale a business, make sure each new unit moves you closer to a stronger company rather than a larger problem. 🚀📊💡