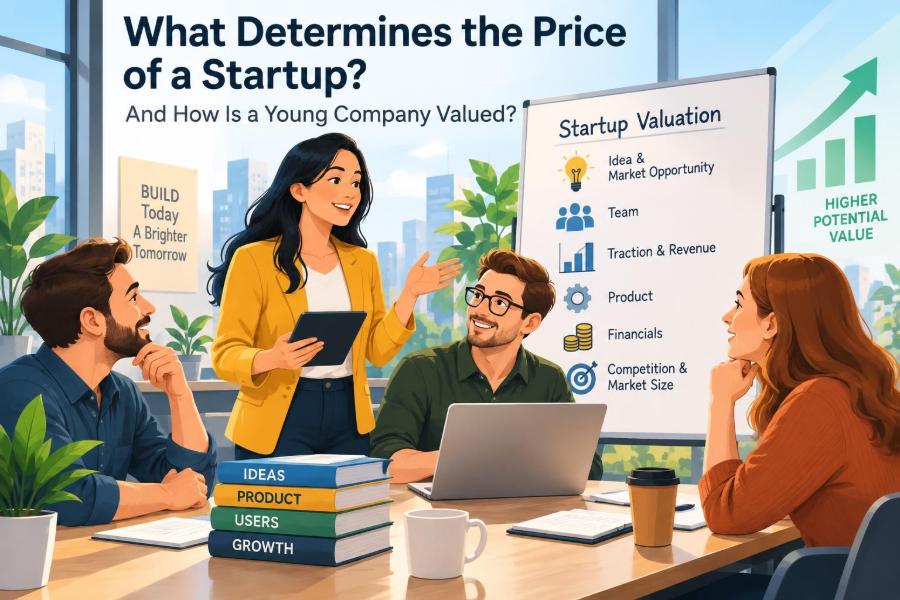

A startup valuation can feel strangely abstract. One founder says their company is worth $2 million before meaningful revenue; another has customers, profit, and a smaller number. Neither figure is automatically right or wrong, because valuation is not a price tag printed by a machine.
This matters if you are raising investment, offering equity to a co-founder or employee, buying a small company, or simply deciding whether your business is becoming a real asset. It suits founders who want to understand the logic behind the numbers before entering a high-stakes conversation.
Right now, investors and buyers are generally paying closer attention to durable revenue, efficient growth, and evidence of customer demand. Big ideas still matter, but the ability to turn an idea into repeatable progress matters more.
The good news is that you do not need to become an investment banker to have a credible view of your company’s value. You need clean information, sensible assumptions, and the confidence to separate what you hope will happen from what your business has already proven.
🧭 1. Start with the real meaning of “valuation”
Valuation is an estimate of what a company is worth at a particular time, under particular terms, to a particular buyer or investor. It is not a universal fact.
A founder may value a startup based on its future potential. An investor values the ownership they might receive and the chance of a future return. A buyer may care mostly about current cash flow, customers, assets, and risk.
- Pre-money valuation: the company’s agreed value before new investment arrives.
- Post-money valuation: pre-money valuation plus the new cash invested.
- Enterprise value: a broader measure often used in acquisitions, considering operations and debt.
- Equity value: the value left for shareholders after relevant liabilities are considered.
For a very early startup, valuation is usually a negotiated estimate. For a mature profitable business, it is more often anchored in financial performance.
💬 2. Understand why a startup’s “price” changes by context
A company can have different reasonable valuations on the same day. Selling 10% to a seed investor, selling 100% to an acquirer, and granting 1% to an early employee are different transactions with different risks and rights.
Investment terms also affect the practical price. Preferences, voting rights, board seats, liquidation terms, and anti-dilution clauses can make two offers with the same headline valuation far from equal.
Simple example
If an investor puts $250,000 into a company at a $1 million pre-money valuation, the post-money valuation is $1.25 million. The investor owns 20% immediately after the round, assuming no other changes: $250,000 divided by $1.25 million.
That does not mean every shareholder can instantly sell shares at that price. Startup shares are usually illiquid, and their eventual value depends on future financing, profitability, or an exit.
🧱 3. Measure the stage before choosing a method
The most useful valuation method depends on how much evidence the company has produced. Trying to value an idea-stage business like a public company creates false precision.
| Company stage | Best evidence | Common valuation approach | Confidence level |
|---|---|---|---|
| Idea or prototype | Founder quality, problem, market insight | Comparable deals, scorecard, milestone-based negotiation | Low |
| Early traction | Users, pilots, retention, early revenue | Comparable deals, venture capital method | Moderate |
| Growing revenue | Recurring revenue, growth, unit economics | Revenue multiples, discounted cash flow | Moderate to high |
| Profitable business | Profit, cash flow, customer concentration | Profit or cash-flow multiples, asset valuation | Higher |
The earlier the stage, the more valuation depends on judgment. The later the stage, the more it depends on records.
🎯 4. Evaluate the problem, not just the product
Investors and buyers pay for a business that solves a painful, frequent, and valuable problem. A polished product without a compelling problem can still be hard to value.
Ask whether customers currently spend money, time, or effort dealing with the problem. A startup serving an urgent workflow, regulatory need, or costly inefficiency may deserve more attention than one offering a pleasant but optional feature.
Practical actions
- Write the customer’s problem in one plain sentence.
- List current alternatives, including spreadsheets, freelancers, and doing nothing.
- Record the economic cost of the problem where possible.
- Collect customer language from sales calls rather than relying on your own wording.
Strong demand reduces market risk. Lower risk can support a stronger valuation.
🌍 5. Size the market honestly
A large market can create upside, but founders often weaken their case by claiming every person or business as a potential customer. A credible market definition starts narrow.
For example, do not begin with “the global retail market.” Begin with a specific segment, such as independent specialty retailers using a particular point-of-sale system in a defined region.
Estimate the number of reachable customers, a realistic annual spend, and the share you could serve over time. Then explain why your first niche can expand into adjacent markets.
Common mistake: confusing a large theoretical market with an accessible market. Investors care about a plausible route to customers, not only an impressive top-down number.
👥 6. Price the quality and completeness of the team
At the earliest stages, the founding team is often the largest part of the valuation argument. Investors are assessing whether this group can learn quickly, sell, build, recruit, and survive setbacks.
Relevant industry knowledge, technical ability, sales experience, and a record of working well together can reduce execution risk. A solo founder can absolutely build a company, but must show a plan for the capabilities they do not yet have.
What to document
- Why the founders understand this customer or problem.
- Who owns product, sales, operations, and technical decisions.
- Key hiring gaps and the intended timing for filling them.
- Evidence that the team can ship and talk to customers.
Do not inflate credentials. Clarity about gaps is more credible than pretending none exist.
📈 7. Treat traction as evidence, not vanity
Traction means proof that customers want and continue to use what you offer. Revenue is powerful evidence, but it is not the only form.
A paid pilot, signed letter of intent, high-quality waiting list, repeated use, renewal, or a short sales cycle can all be useful signals. The strongest signals are difficult to fake and tied to customer behavior.
Metrics worth tracking
- Monthly recurring revenue and its growth rate for subscription businesses.
- Active customers and repeat purchase rate for transactional businesses.
- Retention and churn, measured by customers and revenue.
- Conversion rate from lead to paying customer.
- Sales-cycle length and pipeline value.
- Gross margin and contribution margin.
A large number of free signups means little if almost nobody returns. Show the full story, including weaknesses and what you are doing about them.
💵 8. Make revenue quality a valuation driver
Not all revenue is valued equally. Recurring, diversified, contract-backed revenue is generally more predictable than one-off projects from a few clients.
A software business with customers renewing annually may command a different multiple from an agency with the same revenue, because future income is easier to forecast. That does not make service businesses inferior; it simply means their value is judged through different economics.
| Revenue characteristic | Why it matters | Typical valuation effect |
|---|---|---|
| Recurring subscriptions | Improves predictability | Usually supportive |
| High gross margin | Leaves room to invest and profit | Usually supportive |
| Customer concentration | One lost client can damage the business | Usually negative |
| One-time projects | Requires continual new selling | Often lower multiple |
| Long contracts with clear terms | Reduces uncertainty | Usually supportive |
Keep contracts, invoices, revenue recognition, and customer records organized. Diligence becomes painful when your financial story cannot be verified.
🧮 9. Know the main valuation methods
No single method is perfect. A sensible founder often uses two or three methods to create a range, then explains why the business may sit toward the low, middle, or high end.
Comparable company analysis
This approach examines similar companies or recent transactions and applies relevant revenue or profit multiples. It works best when the businesses truly share growth, margins, geography, customer type, and risk.
Discounted cash flow
A discounted cash flow model estimates future cash and discounts it back because future money is uncertain. It can be useful for established businesses, but early startup forecasts are often too speculative to carry much weight.
Venture capital method
This begins with a possible future exit value, estimates the investor’s desired return, and works backward to a present valuation. It is common in venture discussions, but depends heavily on assumptions about future growth and exit conditions.
Asset-based valuation
This totals relevant assets and subtracts liabilities. It may matter for inventory-heavy or equipment-based businesses, but often understates a software or brand-led startup’s potential.
🔎 10. Use comparable multiples carefully
A multiple is a shortcut, not a verdict. If comparable businesses trade or sell at a multiple of annual recurring revenue, your company does not automatically deserve the same figure.
Adjust for differences in growth, retention, gross margin, customer concentration, geography, size, and profitability. Smaller private companies often face a discount because their shares are difficult to sell and their financial reporting may be less mature.
A simple working process
- Find a small set of genuinely similar companies or transactions.
- Note the metric used: revenue, recurring revenue, earnings, or cash flow.
- Compare the quality of your metrics, not only their size.
- Build a conservative, base, and optimistic range.
- State your assumptions clearly in your investor materials.
Avoid cherry-picking the most famous high-growth company in your category. It can make you look less prepared, not more ambitious.
🛠️ 11. Build a simple forecast that earns trust
A forecast is not a promise. It is a transparent model of what must happen for your plan to work.
Start with operational drivers: leads, conversion rate, average order value, retention, hiring, product capacity, and cost per acquisition. Revenue should emerge from these assumptions rather than appear as a round number at the bottom of a spreadsheet.
Monthly revenue = new customers × average monthly price
Ending customers = starting customers + new customers − churned customers
Gross profit = revenue − direct cost of delivering the service
Show a 12- to 24-month monthly forecast for an early business, with a longer annual view if useful. Maintain a downside scenario. It demonstrates that you understand cash risk.
⚙️ 12. Prove that unit economics can improve
Unit economics show whether each customer, order, or account can create value after direct costs and the cost of acquiring that customer. A young company can lose money while building, but it needs a credible path to healthier economics.
For a subscription company, compare customer acquisition cost with gross profit generated over a customer’s expected lifetime. For a marketplace, examine take rate, repeat transactions, incentives, and support costs. For a service business, track utilization and delivery margin.
- Separate direct delivery costs from general overhead.
- Track acquisition spending by channel.
- Measure payback time, not just lifetime estimates.
- Watch whether retention improves as the product matures.
Do not hide unprofitable customers inside averages. Find out which segments, channels, or packages create the strongest contribution.
🛡️ 13. Account for risk, competition, and defensibility
Valuation rises when risk falls, but no startup is risk-free. Be specific about the risks: regulation, platform dependence, long sales cycles, technical complexity, supply constraints, customer concentration, or aggressive competitors.
Defensibility does not have to mean a patent. It can come from embedded workflows, trusted distribution, proprietary data collected responsibly, strong customer relationships, operational expertise, or a brand that earns repeat business.
Questions to answer before diligence
- Why would a customer stay after trying a competitor?
- What happens if a major platform changes its rules or pricing?
- Which part of the business is hard to copy in practice?
- What regulations, licenses, taxes, or data obligations apply?
Rules vary significantly by country, state, and sector. Seek qualified legal and tax advice before making claims about compliance or structuring an investment.
🤝 14. Negotiate terms, not only the headline number
A high valuation can be expensive if it comes with restrictive terms. Conversely, a slightly lower valuation from a helpful investor with clean terms may give the business more room to grow.
Read and understand equity dilution, investor rights, liquidation preferences, option-pool requirements, pro-rata rights, board control, and future financing obligations. Use a startup lawyer experienced in your jurisdiction when possible.
Common mistake
Founders sometimes optimize for the biggest number because it feels validating. If the valuation is too high for your traction, the next round may be difficult unless the business grows into it quickly.
A sustainable valuation leaves room for future progress. It should be ambitious enough to fund meaningful milestones and grounded enough to support the next conversation.
🧾 15. Prepare your valuation evidence pack
You do not need an elaborate data room on day one, but you do need a trustworthy set of documents. Good preparation speeds up conversations and exposes weaknesses you can fix early.
- Current capitalization table showing every owner and option commitment.
- Monthly profit-and-loss statement, cash balance, and cash burn.
- Customer list with revenue, start dates, renewal status, and concentration.
- Key contracts, intellectual property records, and incorporation documents.
- Product roadmap and evidence of customer demand.
- Forecast with assumptions and downside case.
- A clear explanation of how much you are raising and what milestones it funds.
Keep sensitive customer and employee information protected. Share documents in stages and get professional advice on confidentiality and securities rules where relevant.
🚦 16. Choose the right moment to raise or sell
Timing can change the number dramatically. Raise when you can point to a specific inflection point: a working product, repeatable sales channel, improving retention, major partnership, regulatory approval, or a clear path to profitability.
Waiting is not always possible, especially if cash is short. But if you can reach a meaningful proof point with customer revenue, a smaller bridge, or disciplined cost control, you may reduce dilution later.
If you are selling a business, reduce dependence on yourself before going to market. Document operations, delegate customer relationships, and clean up financial records. Buyers pay more for a company that can run without the owner doing everything.
🧠 17. Avoid the valuation traps that hurt founders
The most damaging errors are usually avoidable. They come from treating valuation as a performance rather than a decision-making tool.
- Confusing revenue with value: growth without margin or retention may not be valuable.
- Using unrealistic forecasts: unsupported assumptions weaken every number that follows.
- Ignoring dilution: calculate ownership after the round, option pool, and likely future rounds.
- Chasing vanity metrics: prioritize retention, conversion, and cash over superficial audience size.
- Hiding problems: experienced investors usually find them; explain the issue and your plan.
- Skipping professional review: legal, accounting, and tax details can materially affect a deal.
Being realistic does not mean being timid. It means presenting an ambitious vision with evidence, milestones, and a sober view of the risks.
✅ 18. Your action plan for this week
You do not need to calculate a perfect valuation before taking action. Start by making the business easier to understand and easier to verify.
- Update your monthly revenue, costs, cash balance, and customer metrics.
- Create a one-page summary of the problem, customer, traction, market, and funding need.
- Build conservative, base, and optimistic forecasts using operational assumptions.
- List three to five truly comparable businesses or transactions, noting key differences.
- Calculate your current ownership and model the dilution from a proposed round.
- Speak with an accountant, lawyer, mentor, or experienced founder in your country before signing anything.
The best startup valuation is not the highest number you can say aloud; it is the number and terms that give a real business the resources and credibility to reach its next meaningful milestone. 🚀📊🤝