
Most startups do not fail because the founder cannot calculate a percentage. They fail because cash problems arrive as a surprise. A product launch slips, a customer pays late, a contractor costs more than expected, and suddenly the bank balance that looked healthy three months ago is nearly gone.
Understanding runway and burn rate is useful whether you are building a software company, opening a local service business, freelancing on the side, or testing an online store. If money is involved, you need to know how long that money can support the work.
This is not just an investor metric. It is a decision-making tool for founders who want to hire responsibly, set realistic sales targets, and avoid panic-driven choices. It matters especially now, when customers can take longer to buy and outside funding is never something you should assume will arrive.
The good news is that you do not need a finance degree or expensive software. You need a clear view of cash, a simple forecast, and the discipline to update both regularly.
🧭 1. Start with the two definitions that matter
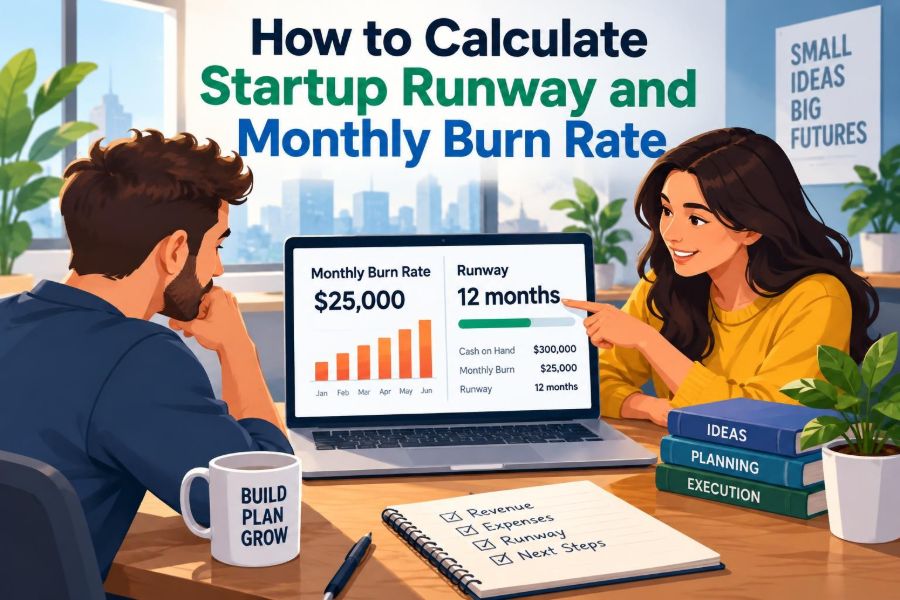
Monthly burn rate is the amount of cash your business uses each month. Runway is the number of months your available cash can sustain that burn.
These terms sound similar, but they answer different questions. Burn rate tells you how quickly the fuel is being used. Runway tells you how far the business can travel before it needs more fuel.
- Burn rate: “How much cash do we lose or spend each month?”
- Runway: “How many months can we keep operating at this pace?”
- Cash balance: “What money is actually available to pay bills today?”
Use cash, not optimism. Signed contracts that have not been paid, hoped-for investment, and a promising sales pipeline should not be treated as cash in the bank.
💵 2. Separate gross burn from net burn
There are two useful ways to measure burn. Tracking both prevents a common mistake: celebrating revenue while ignoring whether the business still consumes too much cash.
| Measure | Simple formula | What it tells you |
|---|---|---|
| Gross burn | Monthly cash outflows | How expensive it is to operate before revenue |
| Net burn | Monthly cash outflows minus cash inflows | How much the cash balance falls each month |
| Runway | Available cash divided by monthly net burn | Estimated months before cash runs out |
Suppose your startup pays $12,000 in salaries, software, rent, contractors, and other expenses during a month. That is your gross burn. If customers pay you $4,000 that month, your net burn is $8,000.
For a pre-revenue startup, gross and net burn may be identical. For a growing business, net burn is usually the more useful number for runway planning.
🏦 3. Define available cash before doing any math
Your runway calculation begins with a conservative number: cash you can truly use to run the business. Open your bank accounts and list the balances rather than relying on accounting reports alone.
Then subtract funds that are already committed. This could include sales taxes collected for the government, payroll taxes, customer deposits you must deliver against, supplier bills due soon, loan repayments, or money legally restricted for another purpose.
A simple available-cash checklist
- Business checking and savings balances
- Cash held in payment processors that is available for withdrawal
- Minus taxes already collected or owed
- Minus payroll, contractor invoices, and supplier bills already committed
- Minus refunds, chargebacks, or deposits you are obligated to return
- Minus a sensible operating buffer for timing surprises
Do not include your personal credit card limit as cash. A line of credit can be a contingency tool, but borrowing to conceal an unworkable burn rate is not a runway strategy.
🧮 4. Calculate your monthly burn rate step by step
Choose a recent period that represents normal operations. Three months is often enough for an early startup; six months can give a steadier picture if expenses move around.
- Add all cash paid out in each month.
- Add all cash received in each month.
- Subtract cash received from cash paid out.
- Average the resulting monthly net burn figures.
Here is a basic three-month example:
January:  $15,000 paid out - $3,000 received = $12,000 net burn
February: $13,000 paid out - $5,000 received = $8,000 net burn
March:    $14,000 paid out - $4,000 received = $10,000 net burn

Average monthly net burn = ($12,000 + $8,000 + $10,000) / 3
Average monthly net burn = $10,000
In a spreadsheet, the basic calculation can look like =AVERAGE(B2:B4)-AVERAGE(C2:C4), where column B is cash out and column C is cash in. Keep the underlying monthly detail; averages are useful, but they can hide a sharp recent increase.
🛣️ 5. Turn burn rate into runway
The standard formula is straightforward:
Runway in months = Available cash / Monthly net burn
If you have $90,000 of available cash and average net burn of $10,000 per month, you have nine months of runway. That does not mean you can wait eight months to act. It means you have nine months before the cash reaches zero under assumptions that may change.
If net burn is zero, the business is cash-flow neutral. If it is negative because cash inflows exceed outflows, you are cash-flow positive and the standard runway formula is no longer the main concern. Your focus shifts to protecting margin, working capital, and sustainable growth.
📅 6. Build a 13-week cash forecast, not just a monthly average
Monthly burn is a strategic dashboard metric. A 13-week cash forecast is an operating tool. It reveals whether you can make payroll next Friday, even when the month as a whole looks fine.
Create one spreadsheet row for each week and estimate beginning cash, expected customer receipts, payroll, taxes, subscriptions, rent, inventory, loan payments, and other outflows. End each week with projected cash.
Why weekly timing matters
A consulting business may invoice $20,000 this month but not receive it for 45 days. Meanwhile, payroll is due every two weeks. Revenue exists on paper, but the cash gap is real.
- Use expected payment dates, not invoice dates.
- Put annual renewals and quarterly tax payments in their actual weeks.
- Mark uncertain receipts separately from committed receipts.
- Compare the forecast with your bank balance every week.
This habit is especially important for inventory, agencies, construction, events, restaurants, and any business with uneven payment timing.
🧱 7. Classify fixed, variable, and one-time costs
Not all costs behave the same way. Classifying them helps you see which reductions are realistic if sales slow down.
| Cost type | Examples | Planning question |
|---|---|---|
| Fixed | Salaries, rent, insurance, core software | How quickly can this be reduced or renegotiated? |
| Variable | Shipping, payment fees, materials, commissions | Does this rise only when revenue rises? |
| One-time | Legal setup, equipment, redesign, launch campaign | Should this be excluded from normal monthly burn? |
Keep one-time costs visible even if you exclude them from your ongoing burn average. A $15,000 equipment purchase can shorten actual runway dramatically, even though it is not a recurring cost.
Also separate costs that are truly essential from costs that are merely familiar. The tool someone “might need later” is different from the tool required to deliver today’s product.
📉 8. Use a conservative revenue assumption
Founders naturally see the upside. Your runway model should protect you from the downside. Include only revenue that is already received, contractually committed with a realistic payment date, or supported by a repeatable sales pattern.
A useful approach is to forecast three cases rather than one:
- Base case: your most reasonable operating assumption.
- Downside case: sales are delayed, churn rises, or a major customer pays late.
- Upside case: sales improve without requiring unrealistic conversion or hiring assumptions.
Do not make the upside case your budget. If you need a near-perfect month to make payroll, the business is already telling you that its plan needs work.
🎯 9. Identify the milestones your runway must buy
Runway is not a trophy. Its job is to buy enough time to reach a meaningful milestone that improves your options. Without a milestone, “we have 12 months left” is only a countdown.
Examples include launching a usable product, reaching a repeatable customer acquisition channel, proving retention, reaching positive contribution margin, signing enough recurring clients, or getting to breakeven.
Ask the hard question
What must be true before your cash runs low? Write the answer in measurable terms. “Grow awareness” is vague; “close five monthly retainer clients worth $2,000 each” is a planning target.
Then work backward. If the milestone requires six months but your downside runway is five, you must reduce burn, increase cash collection, narrow the plan, or find financing now rather than later.
⚖️ 10. Know the difference between profit and cash
A profitable business can still run out of cash. This happens when customers pay slowly, inventory must be bought upfront, taxes are due before invoices clear, or debt payments consume available funds.
The reverse can also happen temporarily: a business can look cash-rich after a loan, prepayment, or investment while losing money every month. That is why your cash forecast and profit-and-loss statement should be reviewed together.
- Profit: revenue minus expenses under accounting rules.
- Cash flow: money physically moving in and out.
- Working capital: cash tied up in receivables, inventory, and short-term obligations.
You do not need to become an accountant, but you do need to ask where cash is getting stuck. An accountant or bookkeeper can be a valuable partner here, particularly as your business adds payroll, inventory, or tax complexity.
🧾 11. Include taxes, debt, and owner pay honestly
Underestimating taxes is one of the fastest ways to create imaginary runway. Sales tax, VAT, GST, payroll tax, income tax, and local obligations vary widely by country, state, and business structure. Treat collected taxes as money you hold for someone else.
Debt principal and interest must appear in the cash forecast, even when accounting treatment makes the numbers look different elsewhere. The bank does not accept an adjusted EBITDA explanation on repayment day.
Owner pay deserves the same honesty. If you are not paying yourself during the first phase, state that explicitly and set a review date. “Free founder labor forever” is not a durable financial model.
🔍 12. Track the metrics that explain the burn
Burn rate is an outcome. To manage it, track the drivers that make it rise or fall. Keep your dashboard simple enough that you actually review it.
Useful monthly metrics
- Beginning and ending cash balance
- Gross burn and net burn
- Runway in base and downside cases
- Revenue collected, not only revenue invoiced
- Accounts receivable aging and overdue invoices
- Gross margin or contribution margin
- Customer churn, cancellations, or repeat purchase rate
- Sales pipeline value and realistic expected close dates
- Payroll as a percentage of total operating costs
A subscription startup may also track recurring revenue and churn. A local service company may care more about booked jobs, labor utilization, deposit collection, and average payment time. Choose metrics that point to a decision.
🚨 13. Set runway warning thresholds in advance
Waiting until cash is nearly gone gives you the worst negotiating position with investors, lenders, vendors, employees, and even yourself. Decide now what actions you will take at different runway levels.
| Runway level | Suggested response |
|---|---|
| 12+ months | Invest carefully, validate growth assumptions, and keep forecasting. |
| 9-12 months | Review major commitments and begin financing or sales plans early. |
| 6-9 months | Freeze nonessential spending, tighten collections, and prioritize one clear milestone. |
| Under 6 months | Move into active cash preservation and make difficult decisions quickly. |
The right threshold depends on your business. A company with predictable renewals and low costs can operate differently from a hardware startup that needs long supplier lead times. The principle is universal: act while you still have choices.
✂️ 14. Reduce burn without cutting the business’s ability to win
The easiest cuts are not always the smartest cuts. If you eliminate the one channel that brings qualified customers, you may extend runway while destroying the path to revenue.
Start by ranking every expense against a near-term outcome: delivering the product, retaining customers, collecting cash, or reaching the next milestone. Pause spending that does none of those things.
Practical ways to lower burn
- Cancel unused software and consolidate overlapping tools.
- Renegotiate vendor contracts before they renew.
- Delay hiring until workload and revenue clearly justify it.
- Use shorter commitments where flexibility matters more than a small discount.
- Reduce broad marketing experiments and focus on measurable channels.
- Ask for deposits, milestone billing, or annual prepayment discounts where appropriate.
- Temporarily simplify product scope and stop low-value projects.
Cut deliberately, not emotionally. Protect customer trust, legal obligations, security, and the people doing essential work.
📈 15. Improve cash inflow before chasing new financing
Raising money, taking a loan, or using a credit line can be sensible. But first look for cash trapped inside the current business. Faster collection and better payment terms can extend runway without giving up ownership.
For service businesses, deposits and milestone invoices can dramatically reduce the gap between doing work and getting paid. For software or membership businesses, annual plans with a modest discount can bring cash forward, provided you can still deliver the service responsibly.
- Send invoices immediately after delivery or at the agreed milestone.
- Make payment instructions simple and offer appropriate payment methods.
- Follow up on overdue invoices on a consistent schedule.
- Review whether customers with slow payment histories need different terms.
- Price work to reflect the cash burden of long payment cycles.
Do not use aggressive collection tactics that damage a valuable relationship. The goal is clear expectations and professional follow-through.
🧑🤝🧑 16. Make spending decisions as a team sport
In a very small startup, one founder may own the finances. Even then, important assumptions should not live only in that person’s head. Share the runway view with co-founders and relevant leaders in plain language.
Team transparency does not mean broadcasting every bank balance to everyone. It means the people making hiring, product, and marketing decisions understand the constraints they are working within.
A useful monthly finance meeting
- Compare actual cash movement with the prior forecast.
- Explain the biggest variances without blame.
- Update expected receipts and major payments.
- Review base, downside, and upside runway.
- Approve or decline major new commitments.
- Assign one owner to each cash-related action.
Consistency matters more than elaborate slides. A 30-minute meeting with accurate numbers is better than a polished quarterly review after the decisions are already made.
🧠 17. Avoid the most common runway mistakes
Most errors are not complicated. They come from mixing time periods, trusting uncertain income, or treating a spreadsheet as a document you build once and never revisit.
- Using revenue instead of cash collected: invoices do not pay salaries until customers pay them.
- Ignoring annual and irregular bills: insurance, renewals, taxes, and equipment purchases still consume cash.
- Calculating from one unusually good month: use a period that reflects normal operations.
- Forgetting founder compensation: unpaid labor can hide the real economics.
- Counting planned funding as current cash: until funds clear, it is a possibility, not runway.
- Assuming cuts happen instantly: contracts, notice periods, and commitments create delay.
- Confusing a credit facility with profitability: debt buys time, not product-market fit.
When in doubt, make the forecast more conservative. Being pleasantly wrong about cash is much easier to manage than being painfully wrong.
🗂️ 18. Use a simple spreadsheet template
You can begin with one workbook containing three tabs: a cash dashboard, a 13-week forecast, and an expense list. A basic system you update weekly is more valuable than sophisticated software nobody maintains.
Cash dashboard columns
Month | Beginning cash | Cash in | Cash out | Net burn | Ending cash | Runway
April | $90,000        | $5,000  | $15,000   | $10,000  | $80,000     | 8.0
On the expense tab, include vendor, amount, payment date, cost type, contract end date, owner, and whether the cost is essential. This becomes extremely useful when you need to make fast, informed trade-offs.
As complexity grows, accounting software and a qualified bookkeeper can save time and improve accuracy. Still, retain a founder-level view of the cash forecast. Delegating bookkeeping is wise; delegating awareness is risky.
✅ 19. Your action plan for this week
You do not need to solve every financial question today. Build a clear starting point, then make the review routine.
- Open your bank accounts and calculate available cash after committed obligations.
- Pull the last three months of cash in and cash out to calculate average gross and net burn.
- Calculate runway using your current net burn.
- Create a 13-week forecast with actual payment dates, including taxes and irregular bills.
- Write one downside scenario in which revenue is late or lower than expected.
- List your top five costs and decide whether each one directly supports the next milestone.
- Schedule a weekly 20-minute cash review and a monthly deeper review.
Runway is not about predicting the future perfectly; it is about seeing the truth early enough to make better choices. Know your numbers, protect your options, and keep building with intention. 🚀💵📊