
Most startups do not fail because the founder cannot attract attention. They fail because they cannot tell whether each new customer makes the business stronger or quietly drains its cash.
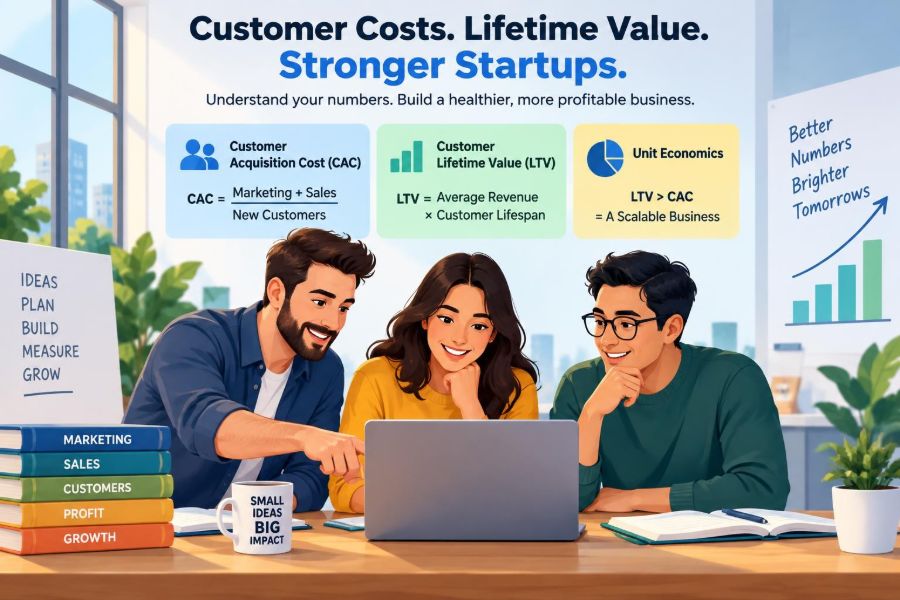
This is where customer acquisition cost, lifetime value, and unit economics matter. They turn a vague feeling of growth into a practical answer to a founder’s hardest question: can we afford to keep growing?
This topic suits anyone selling a product, service, subscription, marketplace offer, or local business experience. You do not need a finance degree, expensive software, or perfect data to start. You need a consistent way to measure the economics of one customer or one order.
It matters especially now because paid attention is competitive, customers compare options quickly, and cash is rarely unlimited. The founders who understand their numbers can test confidently, price more deliberately, and stop unprofitable channels before they become expensive habits.
🧭 1. Start With the Real Question Behind the Numbers
Unit economics describe the revenue, variable cost, and contribution generated by one unit of business. That unit might be one customer, one order, one booked appointment, one delivery, or one active subscriber.
The basic question is simple: after the direct costs of acquiring and serving a customer, does that customer create enough cash to cover overhead and eventually produce profit?
For an online course, the unit may be a paying student. For a coffee shop, it may be an average transaction. For a B2B software company, it is usually an account or subscription customer.
- Choose one unit that reflects how your business earns revenue.
- Use the same definition every month so trends are comparable.
- Separate direct, customer-level costs from fixed business overhead.
- Make decisions from ranges when your data is still incomplete.
Do not wait for a sophisticated dashboard. A spreadsheet with transparent assumptions is much more useful than polished reports built on unclear definitions.
📐 2. Learn the Three Core Metrics First
The three metrics work together. Looking at only one can create a false sense of security.
| Metric | What it tells you | Simple formula | Common use |
|---|---|---|---|
| CAC | What it costs to win a customer | Acquisition spend / new customers | Channel and campaign decisions |
| LTV | Gross profit expected from a customer over time | Customer value × gross margin × lifespan | Pricing and retention decisions |
| Contribution margin | What remains after variable costs | Revenue − variable costs | Order and operating decisions |
| Payback period | How quickly CAC comes back | CAC / monthly contribution | Cash-planning decisions |
CAC is the cost to acquire a new paying customer. LTV, also called CLV, is the gross profit you expect from that customer through their relationship with you. Contribution margin is what a sale contributes toward fixed costs and profit.
Notice the word gross profit in the LTV definition. Revenue is not profit. If you ignore fulfilment, payment processing, support, refunds, or commissions, your LTV will look better than reality.
🎯 3. Define a “New Customer” Before Calculating CAC
A new email subscriber, app download, free trial, quote request, and first paying customer are different events. For most businesses, CAC should use new paying customers.
Choose the event that represents genuine economic commitment. A restaurant might count a first tracked purchase; a consultant might count a signed and paid project; a subscription app might count a customer after their first successful charge.
Useful customer definitions
- Paid acquisition CAC: customers generated by paid marketing only.
- Blended CAC: all sales and marketing costs divided by all new customers.
- Channel CAC: spend and customers tied to one channel, such as search ads or events.
- Incremental CAC: extra spending divided by extra customers created by that spending.
Early on, use paid and blended CAC together. Paid CAC tells you whether a specific tactic works. Blended CAC reveals whether your overall commercial engine is efficient.
🧮 4. Calculate Customer Acquisition Cost Step by Step
The basic formula is:
CAC = Total sales and marketing cost in a period / New paying customers in that periodSuppose you spent $2,400 on ads, $600 on freelance design, and $1,000 of founder time allocated to sales activity in one month. If 40 new paying customers joined, your CAC is:
CAC = ($2,400 + $600 + $1,000) / 40 = $100The difficult part is not division. It is deciding which costs belong in the numerator. Be consistent and write down your policy.
Include these acquisition costs where relevant
- Advertising spend, sponsorships, and paid creator placements.
- Agency, contractor, and campaign-production fees.
- Sales salaries, commissions, and relevant payroll costs.
- Lead-generation software and sales tools.
- Event fees, travel, printed materials, and demos.
- A reasonable allocation of founder selling time once that work is meaningful.
If you exclude sales salaries but include ad spend one month, then reverse the approach next month, your CAC trend is not useful. Consistency beats false precision.
🧾 5. Separate Blended CAC From Channel CAC
Blended CAC answers, “What does a new customer cost our business overall?” Channel CAC answers, “What appears to work inside this channel?” You need both because attribution is imperfect.
Imagine 30 customers arrived after a $1,500 ad campaign, suggesting a $50 paid CAC. But perhaps several had already heard about you through a podcast, a referral, or organic content. Ads may have closed the sale without creating all the demand.
Use channel CAC as a directional tool, not a courtroom verdict. Watch whether total customer growth rises when you increase a channel’s spend. That is closer to understanding incrementality.
A practical early-stage tracking method
- Ask every buyer, “How did you first hear about us?”
- Store one primary source in your customer record.
- Track last-click source separately if your tools provide it.
- Review answers monthly for obvious patterns and gaps.
- Keep a note of campaigns, launches, press, partnerships, and seasonality.
Do not assume tracking software knows the whole story. People often encounter a business several times before buying.
💳 6. Calculate Gross Margin Before You Estimate LTV
Gross margin is the percentage of revenue left after costs that rise directly when you make or serve another sale. It is the foundation of a sensible LTV calculation.
Gross margin = (Revenue − cost of goods sold) / RevenueIf you sell a $100 product and pay $35 for materials, packaging, fulfilment, payment processing, and direct support, your gross profit is $65 and gross margin is 65%.
What belongs in direct costs depends on the model. A digital product may have low delivery costs but meaningful payment fees and customer support. A marketplace may need to include seller payouts, refunds, and transaction costs. A service business should include contractor labor assigned to delivery.
Do not mix these cost categories
- Variable costs: rise as sales rise, such as materials, commissions, shipping, and transaction fees.
- Fixed costs: exist even with no sale, such as basic rent, accounting, or a full-time operations manager.
- Step costs: stay stable for a while, then jump, such as hiring another support person.
Fixed costs still matter deeply, but subtracting them inside every transaction can hide whether the offer itself has healthy economics.
🔁 7. Estimate Customer Lifetime the Honest Way
LTV depends partly on how long customers stay or how often they return. For subscriptions, customer lifetime can be estimated from churn. For non-subscription businesses, use observed repeat-purchase behavior rather than wishful thinking.
If monthly churn is relatively stable, a rough subscription estimate is:
Average customer lifetime in months ≈ 1 / monthly churn rateFor example, a 5% monthly churn rate suggests an average lifetime near 20 months. This is a rough model, not a law. Churn often changes by customer cohort, plan, season, and tenure.
For a retail brand, calculate how many times an average cohort buys over 6, 12, or 24 months. For a project-based agency, estimate expected repeat projects, referrals, and expansion work separately rather than pretending each client subscribes.
New businesses should start with conservative scenarios: short, expected, and optimistic lifetime. Planning around the middle or lower scenario protects cash.
💰 8. Calculate LTV Using Gross Profit, Not Hope
A simple subscription formula is:
LTV = Average monthly revenue per customer × gross margin × average lifetime in monthsSuppose customers pay $40 per month, gross margin is 75%, and estimated average lifetime is 12 months:
LTV = $40 × 0.75 × 12 = $360 gross profitFor a repeat-purchase business, use:
LTV = Average order value × purchases per customer × gross marginIf average order value is $60, the typical customer makes three purchases, and gross margin is 50%, estimated LTV is $90. Add a time period to this figure: “12-month LTV” is much more actionable than an undefined lifetime number.
Do not include hypothetical referral value unless you can measure it. Referrals are valuable, but placing unproven benefits inside LTV is a common way to justify an uneconomic acquisition strategy.
⚖️ 9. Read the LTV-to-CAC Ratio Carefully
The familiar comparison is:
LTV:CAC ratio = LTV / CACUsing the earlier subscription example, $360 LTV and $100 CAC creates a 3.6:1 ratio. On its face, that means each customer may generate $3.60 in gross profit for every $1 spent acquiring them.
A higher ratio is generally better, but it does not tell the whole story. A business with a great ratio and painfully slow payback can still run out of cash. A business with a lower ratio may still be viable if it collects cash immediately, retains well, and has low operating complexity.
| Signal | What it may mean | Founder response |
|---|---|---|
| Below 1:1 | Customer gross profit does not cover acquisition | Pause scale; fix price, margin, retention, or targeting |
| Near 1:1 to 3:1 | May be early, constrained, or weak depending on payback | Investigate cohorts and direct costs |
| Above 3:1 | Potentially attractive economics | Check payback, data quality, and capacity before scaling |
| Very high ratio | Possible opportunity or underinvestment | Test more spend without harming efficiency |
These are discussion prompts, not universal benchmarks. Different sectors, countries, payment cycles, taxes, and capital needs produce different healthy ranges.
⏱️ 10. Measure CAC Payback Period to Protect Cash
CAC payback period estimates how long it takes to recover acquisition cost from customer contribution. This is especially important for subscription and high-upfront-cost businesses.
CAC payback months = CAC / monthly gross profit per customerIf CAC is $100 and a customer contributes $30 gross profit per month, payback is roughly 3.3 months. If it takes 18 months, the customer may be valuable eventually, but you need enough working capital to finance that wait.
Use cash collected when planning survival. An annual prepayment can dramatically improve cash flow even if the eventual LTV is unchanged. A monthly plan may be easier to sell but places more funding pressure on the business.
📦 11. Build an Order-Level Contribution Model
Even businesses with repeat customers need to understand one transaction. Start with net revenue after discounts and refunds, then subtract variable costs.
Contribution per order = Net revenue − direct product/service cost − fulfilment − payment fees − variable supportFor a $80 order, imagine $26 product cost, $8 shipping and packing, $3 payment fees, and $3 expected support and refunds. Contribution is $40 before marketing and fixed overhead.
If the paid acquisition cost per first order is $50, that first order loses $10 before fixed costs. That can be acceptable only if repeat purchases arrive reliably and the business can fund the gap.
Questions to ask for every offer
- What happens to contribution after discounts?
- How do returns, refunds, cancellations, and chargebacks change it?
- Which customers are expensive to serve?
- Does delivery labor expand faster than revenue?
- Can a higher minimum order or bundle improve economics?
🧱 12. Treat Fixed Costs as a Break-Even Problem
After understanding contribution per unit, calculate how many units must be sold to cover fixed operating costs. This gives you a grounded monthly target.
Break-even units = Monthly fixed costs / Contribution margin per unitIf fixed costs are $8,000 per month and contribution is $40 per order, you need 200 orders to break even before taxes and financing costs. This does not mean you should immediately chase 200 orders; it means you know the hill you are climbing.
Costs and tax obligations vary significantly by country and business structure. Confirm sales tax, VAT, payroll charges, import duties, licensing, insurance, and local compliance obligations with qualified local professionals.
🧠 13. Use Cohorts Instead of One Blended Average
A cohort is a group of customers who started in the same period or came from the same source. Cohort analysis exposes whether newer customers behave differently from older ones.
For example, customers acquired through a discount may show a low CAC but cancel quickly. Customers acquired through a webinar may cost more but buy higher-tier plans and stay longer. A blended average would conceal that difference.
Start with these simple cohorts
- Month of first purchase or signup.
- Acquisition channel.
- First product or plan purchased.
- Customer location, if service or regulation differs.
- Business versus consumer customer type.
Review retention, average revenue, refund rate, support demand, and gross margin by cohort. You do not need a complicated data warehouse. A monthly export and a basic spreadsheet can reveal the most important patterns.
🔍 14. Validate Your Numbers With Real Records
Financial models are useful, but bank statements, invoices, payment processor exports, time logs, and accounting records are the reality check. Reconcile your spreadsheet regularly.
Set a monthly finance ritual: close the prior month, count new paying customers, assign acquisition costs, calculate contribution, and compare assumptions with actual behavior. Make one decision from what you learn.
- Match ad-platform spend to bank or card charges.
- Match customer counts to successful payments, not leads.
- Track refunds in the month they occur and by original cohort where possible.
- Record founder and contractor delivery hours.
- Write down changes in pricing, offers, and attribution rules.
Your first model will be wrong. The goal is not to defend it. The goal is to improve it faster than you spend money.
🚫 15. Avoid the Most Expensive Calculation Mistakes
Founders often make numbers look better accidentally because they use revenue where gross profit belongs, leave out labor, or assume every customer will behave like their best customers.
Common mistakes
- Using leads instead of customers: cheap leads are irrelevant if few become buyers.
- Ignoring refunds: gross sales are not the same as retained revenue.
- Excluding delivery labor: a service can look scalable while exhausting the founder.
- Using all-time averages too early: small samples and changing offers distort results.
- Double-counting marketing impact: customers often touch several channels.
- Ignoring payment timing: profitable businesses can still face cash shortages.
- Scaling a weak funnel: more spend magnifies leaks rather than fixing them.
When uncertain, calculate a conservative version and an optimistic version. If the business only works under optimistic assumptions, treat that as a warning rather than a plan.
🛠️ 16. Build a Simple Startup Economics Spreadsheet
Create one sheet for monthly inputs and one for customer cohorts. Keep inputs visible so you can challenge them.
Your monthly input sheet should include
- New customers by channel.
- Ad spend and non-ad acquisition costs.
- Average order value or monthly revenue per customer.
- Discounts, refunds, and chargebacks.
- Direct product, labor, fulfilment, and processing costs.
- Monthly churn or repeat-purchase rate.
- Fixed operating costs and cash balance.
Then calculate paid CAC, blended CAC, gross margin, contribution per unit, estimated LTV, LTV:CAC, payback period, and break-even units. Use formulas instead of typing outputs manually.
Tools can help as complexity grows: a spreadsheet, accounting software, a payment processor export, customer relationship management software, and product analytics may be enough. Buy more software only when manual work is preventing timely decisions.
📈 17. Improve Economics in the Right Order
There are only a few levers: lower CAC, raise price, improve gross margin, increase retention, increase purchase frequency, and reduce servicing costs. The right lever depends on your constraint.
- Fix clear conversion problems before increasing traffic.
- Improve onboarding and delivery before assuming retention is a marketing issue.
- Test pricing and packaging before chasing huge volume.
- Remove costly low-value features, options, or service steps.
- Target customer segments with better fit and lower support burden.
- Expand marketing spend gradually only after payback is understood.
A small price increase can have a large impact on contribution if demand holds. But do not change prices blindly. Test a new package, ask prospects about value, watch close rates, and monitor refund behavior.
🧪 18. Run Small Experiments Before You Scale
A useful experiment has a clear hypothesis, a spending limit, a time frame, and a decision rule. “Let’s run ads and see” is not a real test.
For example: “We believe a niche landing page for independent consultants can produce paid CAC below $120. We will spend up to $600 over two weeks, measure completed purchases, and stop if fewer than five qualified sales result.”
Track these metrics by experiment
- Spend and total cost, including production time.
- Qualified leads and new paying customers.
- Conversion rate at each major stage.
- Paid CAC and early contribution.
- Refunds, cancellations, or activation quality.
- Qualitative buyer feedback and objections.
Small samples are noisy, so do not declare victory from one good day. Still, an early experiment can tell you which assumptions deserve more investment and which deserve to be retired.
🤝 19. Match Your Model to Your Business Type
The formulas are shared, but the operational focus changes by model.
| Business type | Most important early metric | Watch closely |
|---|---|---|
| Subscription software | Payback and retention | Churn, activation, support cost |
| E-commerce | Contribution per first order | Returns, shipping, repeat rate |
| Service business | Gross margin per client | Labor utilization, scope creep |
| Marketplace | Contribution per transaction | Incentives, liquidity, fraud |
| Local business | Customer frequency and capacity | Labor, rent, no-shows |
A consultant may have high CAC but healthy economics if a project is profitable and referrals are measurable. A low-margin physical product needs especially careful attention to shipping, returns, inventory, and cash tied up before a sale.
📊 20. Create a Founder Dashboard You Will Actually Use
Do not build a dashboard with fifty charts. Pick a weekly view for execution and a monthly view for economics.
Weekly operating dashboard
- Cash balance and major upcoming payments.
- Leads, sales, and conversion rate.
- Marketing spend by active channel.
- Orders or new subscriptions.
- Refunds, cancellations, and urgent delivery issues.
Monthly economics dashboard
- Paid CAC and blended CAC.
- Gross margin and contribution per unit.
- Revenue by cohort or channel.
- Retention, churn, or repeat-purchase rate.
- LTV estimate and CAC payback period.
- Break-even volume and progress toward it.
At the end of each month, write three sentences: what improved, what worsened, and what you will test next. This habit creates focus when startup life feels chaotic.
✅ 21. Your Action Plan for This Week
Do not try to perfect every metric immediately. Build a first version, identify the largest unknown, and make one disciplined improvement.
- Choose your economic unit: customer, order, subscriber, booking, or project.
- Export the last 30 to 90 days of sales, marketing spend, refunds, and direct costs.
- Calculate paid CAC and blended CAC using clearly written assumptions.
- Calculate gross margin and contribution for your average sale.
- Estimate a conservative 6- or 12-month LTV based on real retention or repeat behavior.
- Calculate payback period and break-even units.
- Pick one change to test: a price, offer, audience, onboarding step, or fulfilment cost.
Healthy unit economics do not guarantee success, but without them, growth usually makes a fragile business more fragile. Learn the numbers, question the assumptions, and use every customer interaction to build a stronger company. 🚀📊💪